
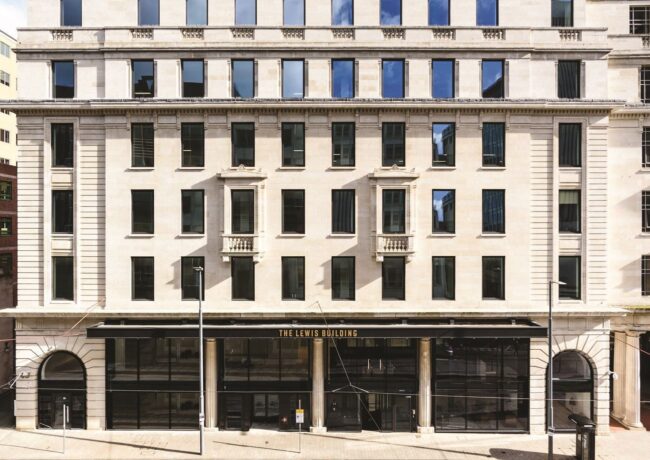
Regional cities on course for highest investment volumes in four years
Avison Young’s Big Nine report states that the total value of workspace transactions outside of London is likely to reach its highest level since 2022, thanks in part to two Q3 deals in Birmingham totalling £148m.
A total of £344m of office deals completed in the third quarter of the year across the Big Nine regional cities: Manchester, Leeds, Newcastle, Birmingham, Edinburgh. Glasgow, Bristol, Cardiff, and Liverpool.
As a result, investment volumes stand at £1.1bn so far in 2026, 25% ahead of the same period in 2025, Avison Young said.
The Big Nine is almost certain to better 2023, 2024, and 2025’s year-end volumes but will have to go some way to topping the more than £2bn recorded in 2022, especially if additional Bank of England rate rises come to pass as predicted.
The quarter’s two most significant deals were in Birmingham where Forma & Patron Capital bought 2 Snowhill for £88m and Martley Capital acquired Priory Court & The Lewis Building for £60m, according to Avison Young. Both deals reflected net initial yields in excess of 10%.
The other large deal of note in Q3 was MDPI’s purchase of 4 Hardman Square in Manchester’s Spinningfields for £20m.
The occupational market experienced a more challenging Q3, during which stronger than expected economic growth did not translate into deals, AY said.
Across the Big Nine, take-up reached 1.7m sq ft in Q3 2026, down 13% on Q2 and 17% below the 10-year quarterly average.
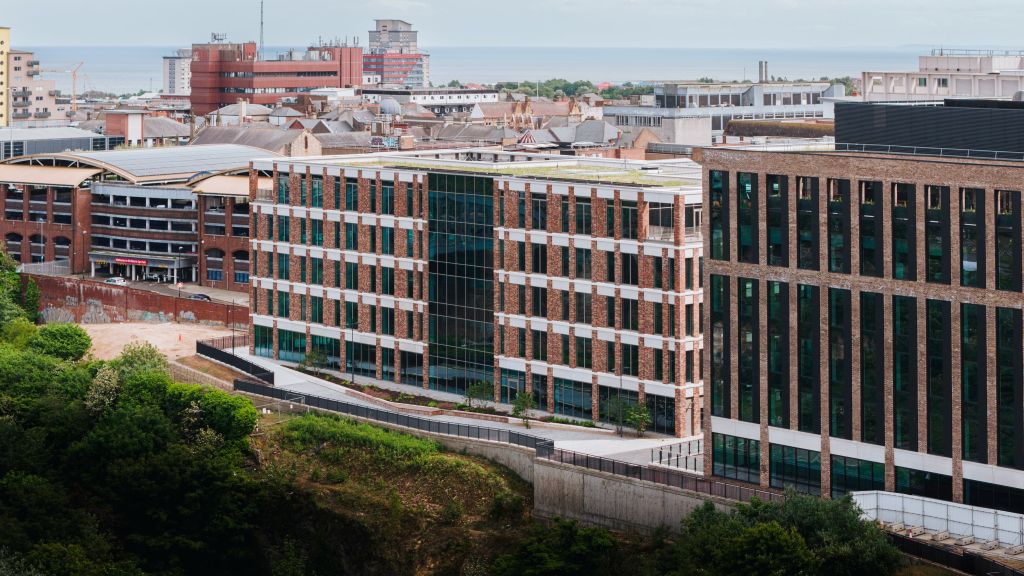
The largest letting of the quarter was actually outside the Big Nine, but AY has counted the 55,000 sq ft DWP deal in Sunderland in Newcastle’s total. Credit: via Creo Comms
Manchester and Leeds both saw take-up fall quarter-on-quarter. The former will require a glut of deals totalling 475,000 sq ft in Q4 to reach its rolling five-year leasing average of 1.1m sq ft. Leeds has recorded 554,429 sq ft of take-up so far this year, which is down 18% compared to the same point last year, according to AY’s findings.
Liverpool’s take-up was up 90% compared to Q2, nudging 50,000 sq ft.
Around 288,000 sq ft was let in Birmingham in July, August, and September, 20% above the city’s 10-year quarterly average.
Take-up in Newcastle tipped over 200,000 sq ft for the quarter, but the largest North East deal was actually in Sunderland, where DWP took 55,000 sq ft at L&G’s Faber.
Guy Spencer, director and head of national capital markets at Avison Young, said: “There are clear reasons for optimism in the regional office investment market. Activity is gathering pace as investors recognise the value available in the regions, particularly in well-located buildings that can provide reliable income and benefit from rental growth.
“The market is not recovering at the same rate everywhere, but that is creating opportunities for buyers who can identify assets with the right fundamentals.”
While construction activity was up 9% year-on-year, Spencer added that a shortage of new-build stock “is becoming increasingly pronounced”.
“Businesses are looking for offices that help them attract talent and meet higher expectations around connectivity and sustainability, but the development pipeline remains limited.
“That imbalance should support higher rents for the best buildings and give investors greater confidence to continue investing in our regional cities into 2027.”